
Whose insurance pays if I'm hurt at a store or someone's home?
Hurt at someone's home or a store? Learn when homeowners medical payments coverage or liability insurance may pay, and how to get the policy in Florida.

Riley Beam
- At a home, homeowners medical payments coverage may pay your bills up to its limit, regardless of fault; if an owner or store is legally responsible, their liability insurance may pay.
- Under section 627.4137, you can ask in writing for the insurer's name, the liability limits and a copy of the policy, due within 30 days.
- Ask the owner or store for its insurance company and a claim number, and keep every medical bill and record of what was paid.
Worried About Your Injury Case? We'll Review It - Free!

Whose insurance pays if you're hurt at a store or home?
If you're accidentally hurt at someone's home, the medical payments coverage in their homeowners policy may pay your medical bills up to its limit, regardless of fault. If the homeowner or a store is legally responsible for your injury, their liability insurance may pay your claim, but coverage varies by company, and Florida law doesn't require homeowners insurance.
Does homeowners insurance cover injuries to others? A homeowners policy normally includes two coverages for that: personal liability and medical payments to others. Medical payments coverage doesn't cover the policyholder, anyone who lives in the home, or activities involving a business run from the home. Personal liability coverage protects the homeowner when they are legally liable (legally responsible) for your injury, and there is a maximum limit. It doesn't cover harm the homeowner or family members who live there caused on purpose, or liability from an automobile accident, and the policy may have other exclusions (things it doesn't cover).
For more on injuries at homes and businesses, see premises liability lawyers in Melbourne.
What does Florida law say about who pays?
Homeowners insurance
The Florida Department of Financial Services' Homeowners' Insurance Toolkit, an official state guide, says "Florida law does not require the purchase of homeowners' insurance," though some cities and counties may require liability coverage for owners of certain pets or a swimming pool. A policy normally includes "Coverage E: Personal Liability" and "Coverage F: Medical Payments to Others," summed up on its declarations page (a summary page in the policy). Specific coverage "will vary from company to company."
Section 627.4137: getting the policy in writing
Under section 627.4137, Florida Statutes, each insurer that "does or may provide liability insurance coverage" must answer "within 30 days of the written request of the claimant" (the person making the claim). Its sworn statement covers each known policy, including excess or umbrella (extra) policies. It lists the insurer's name, each insured's name, the liability limits, any policy or coverage defense (reason it may not cover the claim) it reasonably believes it has, and a copy of the policy. On written request, the insured or their insurance agent must also disclose each known insurer and its coverage, and forward the request to the insurers. So you can find out what coverage exists and how much.
Section 627.4136: suing the insurer comes later
Section 627.4136, Florida Statutes, says someone not insured under a liability policy must "first obtain a settlement or verdict against a person who is an insured" before suing the liability insurer, for a claim the policy covers. A verdict is the decision at trial.
Section 768.0755: a spill in a business
Under section 768.0755, Florida Statutes, if you slip and fall on a "transitory foreign substance in a business establishment" (think of a spill on the floor), you must prove the business had "actual or constructive knowledge of the dangerous condition and should have taken action to remedy it." That means it knew or should have known about it and should have fixed it. The section "does not affect any common-law duty of care" owed by whoever possesses or controls a business premises; common law means rules that come from court decisions.
Section 768.81: shared fault
Section 768.81, Florida Statutes, sets these rules for negligence (carelessness) cases:
- The court enters judgment against each liable party based on its own percentage of fault, "not on the basis of the doctrine of joint and several liability" (a rule that could make one party pay the whole amount).
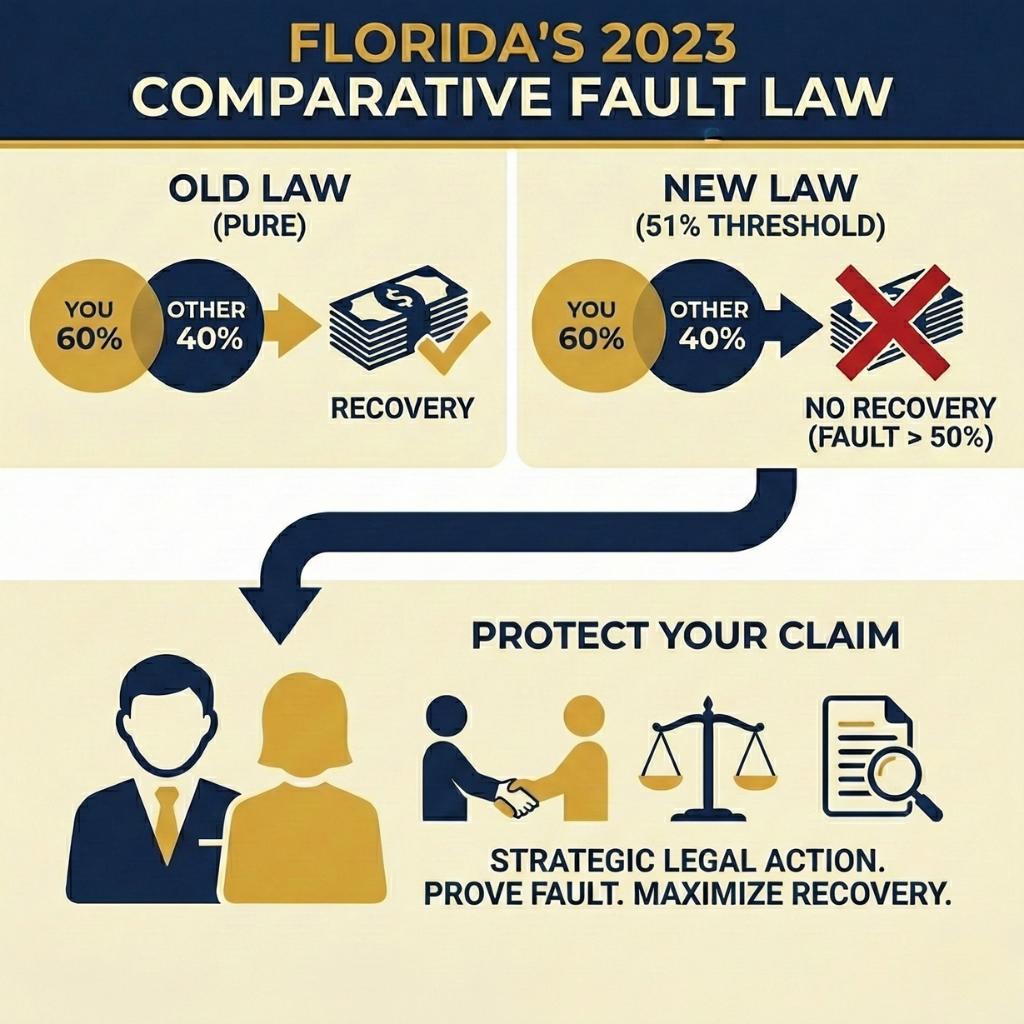
- Your own share of fault reduces your damages (the money you can recover for your harm) proportionately, but does not by itself bar recovery.
- If you are found more than 50 percent at fault for your own harm, you cannot recover any damages. That bar does not apply to injury or wrongful death claims arising out of medical negligence.
The more-than-50-percent bar came from Chapter 2023-15, Laws of Florida, and applies to lawsuits filed after March 24, 2023. Judges decide how the law applies to the facts of each case, and some have ruled differently for injuries that happened before the change, but the law on the books stands.
How do medical payments and liability coverage work?
Hurt at a friend's or relative's home
If you were accidentally hurt and don't live there, the homeowner's medical payments coverage may pay your medical bills up to its limit, regardless of fault, so you don't have to show the owner did anything wrong. If the homeowner is legally liable for your injury, their personal liability coverage may protect them against your claim. The state guide gives this example, written to the homeowner: if a neighbor "slips and falls in your house and sues you, the personal liability coverage would pay that claim as well as legal fees." Ask the homeowner to report your injury to their insurance company and to share the claim number with you.
Hurt at a home someone rents
If the renter has renters insurance, it may also provide personal liability coverage for what the renter becomes legally liable to pay for bodily injury caused by the renter's negligence, including legal defense costs. Its medical payments coverage, if the policy has it, covers visitors' medical and related expenses from personal activities on the property, "typically without regard to" the renter's legal liability. Terms vary between insurance companies, says the state's Renters' Insurance Toolkit.
Who pays my medical bills after a fall at a store?
If the business is legally responsible for your injury, its liability insurance may pay your claim. For a spill, section 768.0755 sets what you must prove. Does business liability insurance pay for a slip and fall no matter who was at fault? Don't assume so: ask the store or its insurer, and use section 627.4137 to get the policy in writing. See Is a store responsible if I slip and fall there?
When more than one party is at fault
Say a store and a company it hired to clean the floors both played a part. Each liable party answers for its own percentage of fault. So you may need a claim against each one.
Hurt by a crime on someone's property
If someone attacked you on a property, the questions are different. See Can I sue a property owner if I was attacked on their property?
What a claim may be worth is a separate question, covered in How much is my personal injury case worth?
What else do people ask about who pays?
Will my friend have to pay out of their own pocket?
If your friend is legally liable, their personal liability coverage may protect them against your claim, and there is a maximum limit for this coverage. Their medical payments coverage can pay your bills up to its limit, regardless of fault, without any claim that your friend did anything wrong. Coverage varies from company to company, and a homeowner may not have a policy, because Florida law doesn't require one.
Can I go straight to the store's insurance company?
You can talk with the insurer's adjuster (the person who handles the claim). But under section 627.4136, you can't sue the liability insurer itself until you first get a settlement or verdict against the store or owner it insures, for a claim the policy covers.
Can my own health insurance pay my medical bills?
You can give your doctors your health insurance as usual. Under section 768.76, Florida Statutes, health insurance payments are "collateral sources" (money for your injury from somewhere other than the person at fault), but Medicare, Medicaid, workers' compensation and certain other government program benefits are not. A health insurer with a right of subrogation or reimbursement (a right to be paid back out of what you recover) that has followed the statute has a right to be repaid by you if you recover all or part of those amounts from the person at fault. That repayment is limited to the amount of those payments you actually recovered, minus its proportional share of your costs and attorney's fees.
What if I was hurt while working at the store or home?
Under section 440.11, Florida Statutes, your employer's workers' compensation liability is exclusive and replaces all its other liability to you and your family, except in situations the statute lists. Under section 440.39, Florida Statutes, if a third party (an outside person or business, not your employer) injured you on the job through negligence or a wrongful act, you can accept workers' compensation benefits and also sue that third party.
What should you do now to get your bills paid?
- Get medical care, and go to your follow-up visits.
- Tell the store manager or homeowner what happened, and ask for their insurance company's name and a claim number.
- If they won't say, send a written request: the insured or their insurance agent must disclose each known insurer, and the insurer must answer within 30 days.
- Keep every medical bill and a record of who paid what.
- Take photos and get witnesses' names. See What should I do after a slip and fall?
- Read anything before you sign it, and talk to a lawyer first.
Under section 95.11, Florida Statutes, a lawsuit for an injury caused by negligence must be filed within two years. That two-year rule applies only to claims that arose after the 2023 change took effect on March 24, 2023, and under section 768.28, Florida Statutes, a negligence lawsuit against a Florida state or local government agency must be filed within 4 years after the claim arises, except medical malpractice and wrongful death claims, which follow the deadlines in section 95.11(5). Before you can sue a government agency, a written claim generally must be presented within 3 years after the claim arises (2 years for wrongful death) and then denied, or left without a final decision for the time the law allows. Older claims follow different rules, explained in How long do I have to file a personal injury claim in Florida?
Talk to a Melbourne premises liability lawyer
Douglas R. Beam, P.A. is a personal injury law firm in Melbourne, Florida. If you were hurt at a store or someone's home, a lawyer can help you find the insurance policies that may apply and request the coverage information in writing. You can talk with us in a free consultation.
Call us at (321) 723-6591, or send us a message through the form on our website. Our office is at 25 West New Haven Avenue, Suite C, Melbourne, FL 32901.
Sources
- Section 627.4137, Florida Statutes
- Section 627.4136, Florida Statutes
- Section 768.0755, Florida Statutes
- Section 768.81, Florida Statutes
- Chapter 2023-15, Laws of Florida
- Section 768.76, Florida Statutes
- Section 440.11, Florida Statutes
- Section 440.39, Florida Statutes
- Section 95.11, Florida Statutes
- Section 768.28, Florida Statutes
- Homeowners' Insurance Toolkit, Florida Department of Financial Services
- Renters' Insurance Toolkit, Florida Department of Financial Services
Not Sure What To Do Next? We Can Help – Fast & Free.


Worried About Your Injury Case?
We'll Review It - Free

Don’t miss an article
Florida law, local insights, and the occasional dog pic.
Delivered straight to your inbox.
More articles
Browse all articles

Free Case Review
Get a complimentary review of your case