
How do I file an insurance claim after a car accident in Florida?
How to file an insurance claim after a Florida car accident: start with your own PIP, then the at-fault driver's insurer. Notice, payment, policy limits.

Riley Beam
- You usually start with your own PIP, which pays part of your medical bills and lost income no matter who was at fault, and may also claim against the at-fault driver's insurance.
- Under section 627.736, PIP benefits are overdue if not paid within 30 days after the insurer gets written notice of a covered loss and its amount.
- Call your insurer and agent right away, follow up in writing, and get first medical care within 14 days from a listed provider, which PIP medical benefits require.
Worried About Your Injury Case? We'll Review It - Free!

How do you file an insurance claim after a car accident?
After a Florida car accident, you usually start with your own insurer, whose personal injury protection (PIP) pays part of your medical bills and lost income no matter who caused the crash. If the other driver caused it, you can also claim against their insurance, or your uninsured motorist coverage if you have it and they have too little.
PIP medical benefits need your first medical care within 14 days after the crash, from a provider type the law lists. If the at-fault driver's car has PIP, pain and suffering can be recovered from that driver only for the kinds of injury the no-fault law lists, explained below and in Can I sue the other driver after a Florida car accident if I have PIP?
For more on Florida crash claims, see car accident lawyers in Melbourne.
What does Florida law say about car accident claims?
Your PIP claim
Section 627.736, Florida Statutes, the PIP law, says an insurer "may require written notice to be given as soon as practicable after an accident." The 14-day rule you may have heard about is for first medical care, not notice. That care must be lawfully provided, supervised, ordered or prescribed by a medical or osteopathic physician, a dentist, a chiropractic physician or certain advanced practice registered nurses, or be provided in a hospital or a facility that owns or is wholly owned by a hospital; a licensed provider of emergency transportation and treatment may also provide it.
PIP pays 80 percent of reasonable expenses for medically necessary care of the kinds the law lists (not massage or acupuncture) and 60 percent of lost income when your injury keeps you from working, up to $10,000 in medical and disability benefits plus $5,000 in death benefits. It pays up to $10,000 for that care if a physician, dentist, physician assistant or advanced practice registered nurse found you had an emergency medical condition, but is limited to $2,500 if a listed provider finds you did not. If no physician, dentist, physician assistant or advanced practice registered nurse has found that you had an emergency medical condition, PIP may pay only up to $2,500. Learn more in Who pays my medical bills after a car accident in Florida?
The no-fault limit on lawsuits
Under section 627.737, Florida Statutes, the owner, driver or occupant of a PIP-insured vehicle is exempt from tort liability (being liable in a lawsuit) for your injury from a crash in Florida to the extent PIP benefits are payable, or would be payable but for an exclusion the PIP law allows, unless you are entitled to sue for "pain, suffering, mental anguish, and inconvenience." You can recover those damages only if your injury includes significant and permanent loss of an important bodily function, a permanent injury within a reasonable degree of medical probability (other than scarring or disfigurement), significant and permanent scarring or disfigurement, or death.
Which insurance company do you file with?
These are general situations, not predictions. Your policies and the facts of your crash decide which coverage applies.
Whose PIP pays
- You own a car: your PIP insurer pays for your injury in Florida while you ride in a motor vehicle, or while you are not in a self-propelled vehicle if the injury is caused by physical contact with a motor vehicle. Here a "motor vehicle" is a self-propelled vehicle with four or more wheels, of a type designed and required to be licensed for Florida highways (section 627.732, Florida Statutes).
- You live in the household of a relative who owns a car, and you don't own a motor vehicle that must carry PIP: the relative's PIP insurer pays in those same situations.
- You were hurt in Florida while riding in someone else's car, or, as a Florida resident, by physical contact with a car while you were not in a self-propelled vehicle: that car owner's PIP insurer pays, but only if you do not own a motor vehicle that must carry PIP and are not entitled to PIP from the insurer of someone who owns one.
When the other driver caused the crash
DFS, the Florida Department of Financial Services, says you may file a claim with the other driver's insurance company but should also notify your own. That company investigates and decides whether to accept liability (a traffic ticket to its driver does not necessarily decide fault), and if it denies liability, DFS says to notify your own insurer so it can pay your claim, if coverage is available. The other driver's property damage liability coverage can pay for damage to other people's property, such as your car.
When you were partly at fault
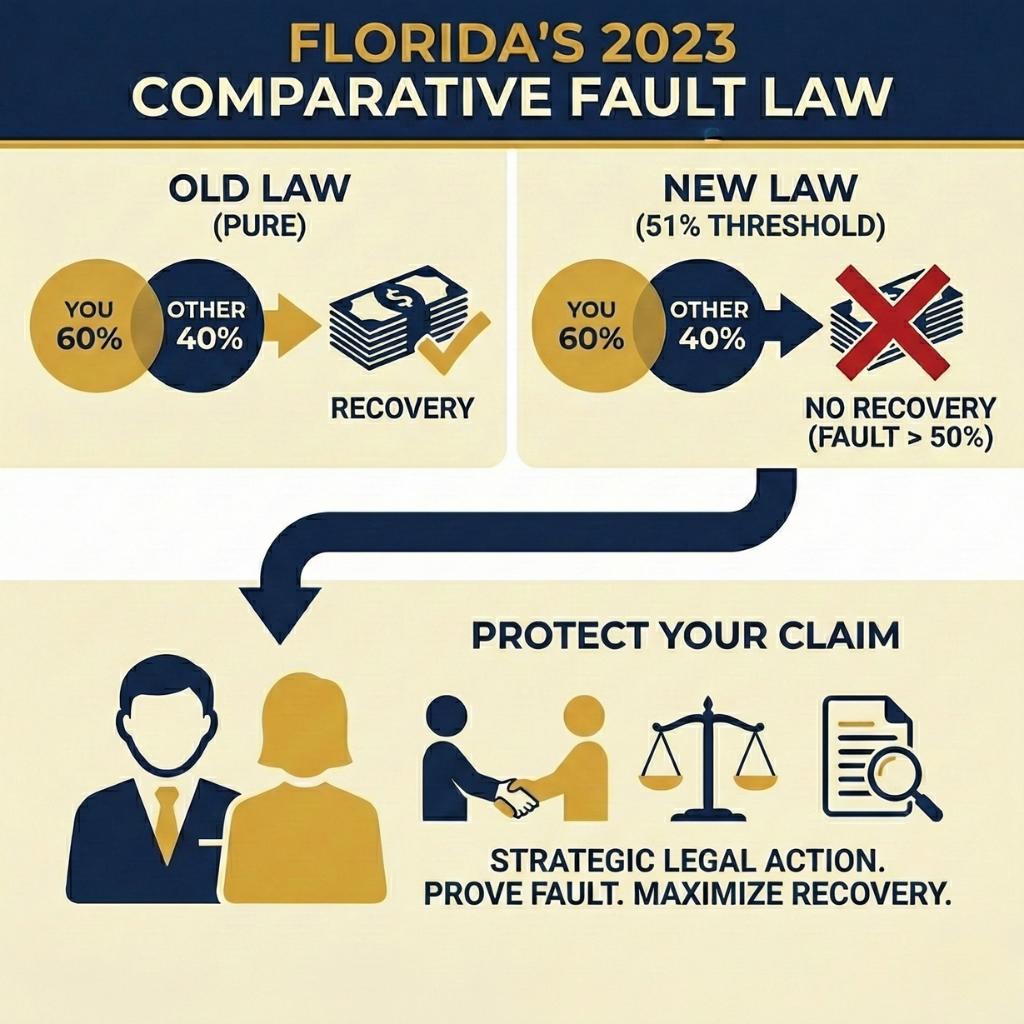
Under section 768.81, Florida Statutes, in a negligence case your share of fault reduces your damages but does not by itself bar recovery. If you are found more than 50 percent at fault for your own harm, you cannot recover any damages, except in medical negligence claims.
More questions about car accident insurance claims
How long does the insurance company have to pay my claim?
PIP benefits are overdue if not paid within 30 days after the insurer gets written notice of a covered loss and its amount, unless it has reasonable proof it is not responsible for the payment. If it reasonably believes fraud was committed, it must tell you in writing within 30 days after you submit the claim, and must deny the claim or pay it with interest within 90 days of submission. For other auto claims, DFS says no Florida statute sets a timeframe for settling (it was answering a question about a car not yet repaired two weeks after a claim). But once you and an insurer agree in writing to settle, section 627.4265, Florida Statutes, says it must pay according to the agreement no later than 20 days after the settlement is reached, and it may require you to first sign a release you both agree to.
How do I find out how much insurance the other driver has?
Under section 627.4137, Florida Statutes, an insurer that does or may provide liability coverage for your claim must give you, within 30 days of your written request, a sworn statement for each known policy listing the insurer, each insured, the coverage limits, any coverage defense it reasonably believes it has, and a copy of the policy. If you don't know the insurer, DFS says you can ask the Florida Department of Highway Safety and Motor Vehicles (FLHSMV) in writing for the other driver's last known insurance company, with a copy of the crash report and your name and address.
What if the other driver has no insurance or not enough?
Your own uninsured motorist (UM) coverage may pay. Under section 627.727, Florida Statutes, a Florida auto policy with bodily injury liability coverage (which pays for injury or death to others) must include UM coverage unless a named insured rejects it in writing for everyone on the policy. A vehicle also counts as uninsured (in other words, underinsured) when its insurer's bodily injury limits are less than your total damages, and UM pays for pain and suffering only if the injury is one of the four kinds listed above. If you agree to settle with the at-fault driver's insurer for less than your full injury claim, written notice must go by certified or registered mail to every underinsured motorist insurer covering you, which has 30 days after receiving it to approve the settlement, or to refuse and pay you the amount of the written offer instead. If it approves or does not respond in time, you may sign a full release for the at-fault driver and their insurer and finish the settlement without harming your UM claim. Learn more in What if the driver who hit me has no insurance or not enough?
What if my insurance company denies or delays my claim?
DFS says the company must explain a denial. DFS asks you to give the company a chance to resolve the issue first (most issues can be resolved within 30 days, it says), then submit a concern online through its Get Insurance Help page. DFS says it cannot give legal advice, decide fault or a claim's value, or force a company to pay if it broke no law, rule or policy provision. Before suing a PIP insurer for benefits, you must send it written notice of intent to sue (a demand letter), and not until the claim is overdue, including any extra time the law gives the insurer to pay. If the claims don't resolve, a lawsuit may be next; see What are the steps in a personal injury claim in Florida?
What should you do now to protect your claim?
- Call the police when the law requires it: after a crash that causes injury, death, or apparent damage of at least $2,000 to any vehicle or property, a driver must immediately notify the local police (inside a city), or otherwise the county sheriff or the nearest Florida Highway Patrol station. The $2,000 figure in section 316.065, Florida Statutes, took effect October 1, 2026; before then it was $500.
- Get medical care within 14 days from a listed provider; PIP medical benefits require it.
- Call your insurance company and agent right away. DFS warns that the company may deny payment if you do not report the accident in a timely manner. Your PIP insurer may require written notice as soon as practicable, so follow up in writing, send your bills and proof of lost income, and keep copies.
- Check before you sign. DFS says that if you file with your own insurer, you should not sign any release of liability from the at-fault driver's insurer, and that it is a good idea to check with your own insurer before signing anything from the other driver or their insurer. If you also have an uninsured motorist claim, the notice steps described earlier on this page explain when you can sign a release for the at-fault driver and their insurer without harming it.
- Know your deadline. Under section 95.11, Florida Statutes, a lawsuit for an injury caused by negligence must be filed within two years. That two-year rule applies only to claims that arose after the 2023 change took effect on March 24, 2023, and under section 768.28, Florida Statutes, a negligence lawsuit against a Florida state or local government agency must be filed within 4 years after the claim arises, except medical malpractice and wrongful death claims, which follow the deadlines in section 95.11(5). Before you can sue a government agency, a written claim generally must be presented within 3 years after the claim arises (2 years for wrongful death) and then denied, or left without a final decision for the time the law allows. Older claims follow different rules, explained in How long do I have to file a personal injury claim in Florida?
Talk to a Melbourne car accident lawyer
Douglas R. Beam, P.A. is a personal injury law firm in Melbourne, Florida. A lawyer can help you sort out which policies apply to your crash and can deal with the insurance companies for you. You can talk with us about your claims in a free consultation.
Call us at (321) 723-6591, or send us a message through the form on our website. Our office is at 25 West New Haven Avenue, Suite C, Melbourne, FL 32901.
Sources
- Section 627.736, Florida Statutes
- Section 627.737, Florida Statutes
- Section 627.727, Florida Statutes
- Section 627.732, Florida Statutes
- Section 627.4137, Florida Statutes
- Section 627.4265, Florida Statutes
- Section 768.81, Florida Statutes
- Chapter 2023-15, Laws of Florida
- Section 316.065, Florida Statutes
- Chapter 2026-39, Laws of Florida
- Section 95.11, Florida Statutes
- Section 768.28, Florida Statutes
- Florida Department of Financial Services, Automobile Insurance Toolkit
- Florida Department of Financial Services, Get Insurance Help
- Florida Department of Financial Services, Automobile Insurance FAQs
- FLHSMV, Florida Insurance Requirements
Not Sure What To Do Next? We Can Help – Fast & Free.


Worried About Your Injury Case?
We'll Review It - Free

Don’t miss an article
Florida law, local insights, and the occasional dog pic.
Delivered straight to your inbox.
More articles
Browse all articles

Free Case Review
Get a complimentary review of your case